What The Markets Are Telling Us About The Election

What The Markets Are Telling Us About The Election

This op-ed by Bob Rubin originally appeared on The Daily Caller here: https://dailycaller.com/2024/08/06/bob-rubin-what-the-markets-are-telling-us-about-the-election/ 


With the U.S. stock markets and markets around the world in free fall yesterday, it is a good time to walk conservatives in America through how a Vice President Kamala Harris or a former President Donald Trump presidency would affect your wallet and checkbook.


Today we see the markets rebounding a little bit, but this market volatility is not good for U.S. industries and retail investors.


As the U.S. political landscape shifts, investors are keenly observing the potential economic impacts of a Harris presidency versus Trump’s return. Both scenarios offer distinct paths for key industries, retail investors and the broader economy. Let’s jump in and analyze both scenarios.


Consider first the economic impact of Harris becoming president. She is known for her advocacy of stronger regulatory measures, particularly in healthcare, technology and finance. While these regulations aim to protect consumers and ensure fair competition, they could also lead to increased compliance costs while impacting profitability, especially for tech and financial firms. The potential for more stringent oversight could reshape industry practices and innovation.


Harris has also expressed support for a balanced energy policy, combining renewable energy initiatives with the continued use of fossil fuels like natural gas. Recently, she has stated she would not ban fracking, reflecting a politically pragmatic approach to maintaining energy sector jobs while advancing environmental goals. This dual strategy hopes to support a transition to cleaner energy without disrupting the existing energy infrastructure.


Now consider the economic policies and market reactions that could come with Trump’s potential return. His economic agenda focuses on deregulation and revitalizing American manufacturing and energy production. He advocates reducing regulations on the oil and gas industries and expanding domestic energy projects, including offshore drilling. This approach is expected to benefit traditional energy sectors, manufacturing and the auto industry, potentially lowering operational costs and boosting economic growth.

In a significant shift, Trump has endorsed cryptocurrency, including accepting Bitcoin donations for his campaign. His support for digital assets represents an interesting generational play, particularly targeting younger demographics not typically aligned with his voter base. This endorsement suggests policies that could foster regulatory support and infrastructure development for cryptocurrencies, positioning the U.S. as a leader in the digital economy. His interest in crypto, alongside a surprise endorsement for eliminating taxes on restaurant workers’ tips, highlights a unique focus on boosting disposable income for younger, often overlooked worker groups.


Then there is the potential impact on the tech industry with J.D. Vance serving as Trump’s vice president. Vance’s deep connections to the tech world could significantly influence the administration’s approach to technology policy. His background — bolstered by support from Peter Thiel and other tech industry figures — suggests a potential for more nuanced technology policies under a Trump-Vance administration. This could include favorable conditions for tech companies, possibly balancing deregulation with strategic oversight to foster innovation while addressing concerns about data privacy and market competition. Additionally, Vance’s Silicon Valley connections might encourage more robust engagement with emerging technologies, including artificial intelligence and blockchain, aligning with Trump’s broader pro-business and deregulation stance.


The potential presidencies of Harris and Trump present contrasting economic visions. Harris’ policies may lead to increased regulation and a focus on renewable energy, potentially challenging traditional sectors but supporting environmental sustainability. In contrast, Trump’s approach likely favors deregulation, traditional energy sectors and an expansion of the cryptocurrency market.


If Harris wins, the market may experience increased regulation, potentially cooling growth in some sectors while supporting green technologies and healthcare reforms.


If Trump wins, we might see a continuation of pro-business policies, including tax cuts and deregulation, likely stimulating sectors like consumer cyclicals, energy and technology, alongside a potential boost from the burgeoning cryptocurrency market.


Investors should weigh these potential outcomes and diversify their portfolios to navigate the uncertainties of the upcoming election. Staying informed about policy developments will be crucial for making strategic investment decisions.


As we approach this momentous election in November, I anticipate that all Americans will be asking themselves this question: “Am I better off financially today than I was 4 years ago?” We all know the answer to that question is that we are not.
bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.
The Dollar Is In Trouble And The Stakes Couldn’t Be Any Higher

The Dollar Is In Trouble And The Stakes Couldn’t Be Any Higher

This op-ed by Bob Rubin originally appeared on Daily Caller here: https://dailycaller.com/2024/07/12/opinion-the-dollar-is-in-trouble-and-the-stakes-couldnt-be-any-higher-bob-rubin/ 


The Republican National Committee’s platform committee adopted a new GOP platform on Monday that promises to do the following if the Republicans win the House, the Senate and the White House: “KEEP THE U.S. DOLLAR AS THE WORLD’S RESERVECURRENCY.”


As someone who manages hundreds of millions of dollars all day long, I must say this is music to my ears and it should be to any and all Americans.


I say this because right now we are on the cusp of seeing the U.S. dollar cast to the sidelines and President Joe Biden and Democrats couldn’t care less! If the U.S. dollar no longer dominates on the world stage, we, the American people, are the ones who will feel this pain.


In recent months, a troubling trend has emerged on the global economic stage: Powerful nations like the Kingdom of Saudi Arabia, Brazil and China are actively sidelining the U.S. dollar in their international trade. This shift, which sees these economic powerhouses increasingly conducting business in other currencies marks a significant departure from the dollar’s long-standing dominance as the world’s reserve currency. 


We must confront the realities of this development and consider its profound implications for our nation’s economic stability and geopolitical influence.

For decades, the U.S. dollar has enjoyed unparalleled status as the currency of choice for international trade and finance. This dominance has afforded the United States significant economic advantages, including lower borrowing costs and the ability to run trade deficits without immediate consequences.


However, recent actions by Saudi Arabia, Brazil and China signal a growing discontent with the dollar’s hegemony and a concerted effort to establish a more multipolar currency landscape.


Saudi Arabia’s decision to diversify its trading apparatus away from the dollar is particularly noteworthy and many believe it is a direct shot across the bow of the Biden Administration. Historically, the petrodollar system — wherein oil transactions are conducted in U.S. dollars — has been a cornerstone of American economic policy and a critical component of our strategic alliance with the Saudis.


This shift by Riyadh not only undermines the petrodollar system but also reflects a broader reorientation of Saudi economic and geopolitical priorities, increasingly aligning with China and other non-Western powers.


Brazil and China for their part have been vocal proponents of de-dollarization. Brazil, under President Lula da Silva, has been pushing for greater economic independence from the United States, advocating for a regional currency in South America. China, meanwhile, has been strategically promoting the use of the yuan in international trade, leveraging its massive economic clout to establish bilateral trade agreements that bypass the dollar.


The consequences of these developments for the American people are profound. Firstly, the erosion of the dollar’s dominance could lead to higher borrowing costs for the U.S. government. Without the privileged status of the dollar, the cost of financing our national debt could rise, necessitating either higher taxes or cuts to essential services.


This scenario poses a direct threat to the financial well-being of American families, particularly those who are already struggling with economic uncertainties.


As the dollar loses its luster, foreign investors may seek safe havens for their capital, leading to a potential outflow of investment from the United States. This capital flight could stifle economic growth, result in job losses, and undermine the prosperity that Americans have long taken for granted.


Beyond the economic ramifications, there are significant geopolitical stakes at play. The dollar’s dominance has been a pillar of American global influence. It has enabled us to impose economic sanctions on rogue states, support our allies, and project power across the globe.


As more countries move away from the dollar, our ability to leverage economic tools in the service of our foreign policy objectives diminishes. This erosion of influence could embolden adversaries and undermine our position on the world stage.


In response to this emerging challenge, it is imperative that we adopt a robust and forward-looking strategy. We should address the root causes of global disenchantment with the dollar. This involves promoting sound fiscal policies, reducing our national debt for once, and restoring confidence in the stability and reliability of the U.S. financial system.


Next, we must reinvigorate our alliances and strengthen our economic partnerships. By fostering closer ties with both traditional allies and emerging economies, we can counterbalance the influence of nations seeking to undermine the dollar. (RELATED: An Endless Wave Of US-Led Sanctions Might Be The Greatest Gift China Has Ever Received)


This requires a nuanced approach that combines economic incentives with strategic diplomacy — an approach that President Biden is clearly incapable of planning and executing.

Lastly, we must champion innovation and competitiveness at home. By investing in cutting-edge industries and ensuring that American businesses remain at the forefront of global trade, we can enhance our economic resilience and reduce our vulnerability to external shocks.


The sidelining of the U.S. dollar by the Saudis, Brazilians and Chinese is a stark reminder that we cannot afford to rest on our laurels and that when America projects weakness on the world stage, this is the end result.


As Americans, we must rise to the occasion, championing policies and politicians that safeguard our economic future and reaffirm our leadership on the world stage. The stakes are high, but with determination and foresight we can navigate these challenges and secure a prosperous future for generations to come.


Given the complexities of the current economic landscape, it is more important than ever to have a financial advisor who understands the geopolitical factors affecting your portfolio. At Rubin Wealth Advisors, where investing meets Conservative values, we can help navigate these turbulent times, ensuring your investments are safeguarded against global uncertainties. Schedule an appointment with us today by clicking here. 

bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.
EXCITING 529 PLAN RULE CHANGES WHAT’S NEW FOR 2024

Exciting 529 Plan Rule Changes: What’s New for 2024

New rules for 529 college savings plans have gone into effect for 2024, providing even greater advantages for families looking to save for college in a tax-advantaged manner. Previously, concerns about potential penalties for non-qualified withdrawals may have deterred some from fully embracing 529 plans. However, recent rule changes have transformed this concern into a significant advantage.


One of the major updates allows for the transfer of unused funds to a Roth IRA account in the beneficiary’s name. This means that even if your child decides not to go to college or receives scholarships that reduce the need for the 529 funds, you can still utilize these savings in a highly beneficial way.


New 529 Rules for 2024


Funding higher education can be burdensome, but a few new rules in 2024 will make it easier for students and student loan holders.


1. 529-to-Roth IRA Rollover


One of the reasons parents and others may have hesitated to contribute to a 529 plan in the past is the limitation on how those funds could be used. Funds could only be withdrawn for qualified expenses related to education, and any non-qualified withdrawals were subject to normal income tax plus a 10% federal tax penalty.


But what if your child decided not to go to college, or they received scholarships or other financial aid and didn’t require all the funds in your 529 account?


The recent rule change has had a big impact. It allows 529 plan beneficiaries to transfer unused funds without a penalty or paying taxes.


2. Secure 2.0 Act


Under the Secure 2.0 Act, the IRS tax code allows tax and penalty-free 529-to-Roth IRA rollovers starting in 2024, provided certain conditions are met. The conditions include:


– Beneficiaries are allowed to roll over up to $35,000 over their lifetime into a Roth IRA in their name (not the original 529 account holder’s name).


3. Gift Tax Increase


In 2024, the gift tax limit has been raised from $17,000 in 2023 to $18,000. Because contributions to a 529 plan are considered gifts, individuals can contribute up to $18,000 per year to a beneficiary’s 529 account without filing a gift tax return. Married couples filing jointly can contribute up to $36,000.

Other Recent 529 Plan Updates


Tax and regulation changes and interpretations are consistently updated for improved understanding and implementation. 529 plan updates are no exception, so here are some of the more recent updates that impact 529 plan holders and those thinking about opening a 529 savings plan.


  1. Qualified Education Expenses

Qualified education expenses include those that you can pay for out of a 529 savings account. These are primarily educational expenses, but that definition has been broadened over the years.


  1. Student Loan Repayments

The SECURE Act of 2019 allows beneficiaries of 529 savings plans to pay for student loans up to $10,000 over their lifetime. Since 529 plan funds don’t expire, distributions can be used to pay for student loan repayments for beneficiaries or their siblings.


  1. Apprenticeship Programs Funding

Qualified apprenticeship programs and their associated expenses are considered educational expenses and can be paid for with 529 plan distributions

.

  1. 529 Plans Can Be Used For K-12 Education

In 2017, a tax reform package expanded the benefits of 529 plan qualified expenses, including private school expenses for K-12 education programs. These qualified expenses are limited to $10,000, but they can be used to help pay for elementary, middle, and high school programs.


  1. Transferring 529 Plan Funds to an ABLE Account

The same 2017 reforms allow funds transfers from a 529 plan to a qualified 529 ABLE Account, created by the 2014 Achieving a Better Life Experience (ABLE) Act. Americans with disabilities can save money for college and other expenses in a tax-deferred ABLE account to supplement private insurance and public benefits.


Maximize the Benefits of New 529 Rules and Roth IRA Rollover


So, how should you and your family take advantage of these recent changes? Here are some ways to benefit from the plan updates in 2024. Work with a plan advisor, financial advisor, or tax professional in your state to maximize your financial and state tax benefits.


– Enroll in a 529 plan.

– Gift up to $18,000 annually to your child or grandchild, or more if you take advantage of superfunding.


– Pay directly to your grandchild’s institution tax-free and lower your taxable estate.


– Pay down student loans with your 529 plan funds.


– Use 529 plan funds for your child’s K-12 education or apprenticeship.


– Transfer unused 529 funds to a Roth IRA retirement plan.


New Benefit: Student Loan Payment Retirement Account Matching


If you’ve completed college and are still paying down your student loans, you have a new option for retirement savings. Many people are still in student loan debt, so they defer beginning to save for retirement and have missed out on employee match programs.


Starting in 2024, Section 110 of the SECURE 2.0 Act helps employees with student debt to save for retirement by allowing employers to make matching contributions to their retirement plans, provided they make qualified student loan payments.


This applies to 401(k), 403(b), SIMPLE IRA, and section 457(b) plans. Talk to your employer about this option to help you start saving for retirement while still paying off student loans.


Work with Rubin Wealth Advisors


Understanding and maximizing the benefits of these new 529 plan rules and Roth IRA rollovers can be complex. It’s important to work with the advisors at Rubin Wealth Advisors to help you navigate these changes and make the most of your financial opportunities. Our team is here to ensure you and your family can fully benefit from these updates, secure your financial future, and achieve your educational and retirement goals.

bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.
financial advisors

Here’s the real reason AI can never replace financial advisors

This article originally appeared on Fortune Magazine: https://fortune.com/2024/01/05/reason-ai-replace-financial-advisors-wealth-bob-rubin/


In the ever-evolving landscape of financial services, one of the most transformative developments in recent years has been the integration of artificial intelligence (AI) into wealth advisory practices. While we should most certainly embrace AI, we cannot forget that client-to-advisor relationships must always be personal and driven by humans.


This marriage of advanced technology with the art of people-to-people financial management holds significant implications for advisors and clients, ushering in a new era of efficiency, personalization, and data-driven decision-making.


With that said, AI in wealth management isn’t about replacing human advisors; rather, it serves as a powerful tool to augment our capabilities.


While we can use this technology to the benefit of our clients, we must not lose sight of the fact this is a people-to-people business. Our clients don’t want to have their money managed by a robot, they want us, the advisors at the helm.

Wealth is personal

Trust is a cornerstone of any successful advisory relationship. AI can process information, but it lacks the emotional intelligence that is necessary to build trust and rapport with clients. Human advisors can establish a connection, instill confidence, and navigate delicate financial discussions with empathy.

For wealth advisors, AI does offer a plethora of advantages, the most prominent being enhanced data analysis. With the ability to process vast amounts of financial data in real time, AI algorithms can identify trends, assess risks, and uncover opportunities that may elude even the most seasoned human advisors.


One key area where AI proves invaluable is in day-to-day portfolio management. Through machine learning algorithms, wealth advisors can optimize investment strategies based on historical data, market trends, and individual risk tolerance. This level of precision allows for more tailored and diversified portfolios, ultimately maximizing returns for clients while managing risks prudently.


AI also facilitates a more personalied client experience. By analyzing client behavior, preferences, and financial goals, wealth advisors can use AI to customize their advice and recommendations. This not only fosters stronger client-advisor relationships but also ensures that financial plans align closely with the unique needs and aspirations of each individual.

Striking the right balance

Critics may express concerns about the potential depersonalization of financial advice with the increasing role of AI. However, the reality is quite the opposite. While AI handles data processing and analysis efficiently, human advisors bring a nuanced understanding of individual circumstances, empathy, and the ability to navigate the emotional aspects of financial decision-making. The collaboration between human advisors and AI creates a synergy that optimizes both the analytical and emotional dimensions of wealth management.


It’s incumbent on all wealth advisors to embrace AI in our wealth advisory practices because it aligns with the principles of efficiency, innovation, and individual empowerment. The ability to harness the full potential of technology ensures that fiscal responsibility and prudent financial management are upheld in an increasingly complex financial landscape.


Nevertheless, it is crucial to recognize that the integration of AI in wealth management comes with its own set of challenges, including issues related to data privacy, security, and the need for regulatory frameworks to keep pace with technological advancements. Striking the right balance between innovation and safeguarding client interests should remain a priority for both wealth advisors and policymakers.


As we navigate this evolving landscape, financial advisors should embrace the possibilities that AI brings while remaining vigilant in addressing the ethical and regulatory considerations that accompany such advancements.


AI can help in many ways–but nothing will ever replace the personal relationship between an advisor and their client.

bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.

Downgrading Israel’s credit rating is a mistake

Downgrading Israel’s credit rating is a mistake

Less than two weeks after the Oct. 7 massacre of 1,400 Israelis, the world is predictably starting to turn on Israel, whether it’s at the United Nations, in the international media or now in the financial markets.


Last week, major rating agencies, including S&P Global Ratings, Fitch Ratings and Moody’s took the perplexing step of downgrading Israel’s credit outlook to “negative.” Their rationale? The anticipation of a war negatively impacting the country’s economy.


It is a grave mistake, however, to underestimate a nation armed with nuclear capabilities, one of the world’s most formidable armies and a highly advanced air force when it faces a barbaric Islamic terrorist organization.


The downgrades echo past rating agency errors and raises questions about the influence of politics on their decisions.

Israel is no stranger to adversity and its security situation has always been a challenging one. However, the idea that the country would be severely hindered by a terrorist organization is both misguided and underestimates the capabilities of the Israel Defense Forces (IDF). The downgrades appear to ignore the historical resilience and strength of Israel in the face of security threats.


Israel’s economic growth has, in large part, been driven by its thriving technology and innovation sector. The nation is a global technology powerhouse, often referred to as the “Startup Nation.” In my last op-ed in JNS, I wrote in detail about how Israel’s startup ecosystem continues to thrive and has always grown in the face of adversity.


The credit rating agencies’ past misjudgments, such as their failure to predict the severity of Greece’s financial crisis or the collapse of Lehman Brothers and near-collapse of AIG during the 2008 financial crisis, should give us pause. These errors had far-reaching consequences, underscoring the fallibility of rating agencies when it comes to assessing complex situations.


The timing of the downgrade also raises concerns about political influence. Historically, credit rating agencies have faced criticism for potential conflicts of interest and for being influenced by political considerations.


Amidst the uncertainty created by these downgrades, there’s an important point to consider: Israel may present an attractive investment opportunity. The resilience of its economy, its strong technology sector and its historical ability to overcome challenges suggest that it might be a prudent time to consider such investments.


The downgrades are questionable moves that warrant scrutiny from within and outside of Israel. Israel’s economic and military strengths should not be underestimated, and in my opinion, the credit rating agencies’ assessments should be taken with a grain of salt.


As history has shown, Israel has faced adversity before and emerged stronger. Its credit rating should reflect this reality rather than succumbing to unfounded pessimism. For investors, this could be an opportune time to explore the potential that Israel offers in terms of economic growth and innovation.

bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.
Daily Caller

BOB RUBIN: The Stone Cold Truth About Bidenomics

Original article appeared on Daily Caller: https://dailycaller.com/2023/10/17/opinion-the-stone-cold-truth-about-bidenomics-bob-rubin/ 


The term “Bidenomics” has become synonymous with the economic policies of the Biden administration and let’s be frank, they have failed on every possible level. I can’t bite my tongue any longer on this. Bidenomics is not only crushing the American spirit but it’s making millions of Americans dependent on our government, which is not the American dream and will have chilling effects on the future of this nation.


While presented as a plan to bolster the financial well-being of Americans, a closer look at the Bidenomics fact sheet reveals a different story — one where the average American is shouldering the burden of inflation and increasingly high interest rates due to Bidenomics.


The effects of these policies are far more pronounced than what the media and the administration are willing to admit. So while the media and the Biden administration is not willing to speak the truth, I will speak out on this.


Recent data from the U.S. Census Bureau, analyzed in depth by Stephen Moore in his recent New York Post op-ed, paints a troubling picture of the state of poverty in America.


What’s most shocking in this data is the sharp increase in poverty rates for both adults and children. In just a year, from 2021 to 2022, poverty in America rose from 7.8% to 12.4%, marking an alarming increase of 58.9%. Equally concerning is the fact that the child poverty rate also doubled, soaring from 5.2% to 12.4%.

The question we must ask is this: How is Bidenomics working for the American people if over 10% of our nation’s children are living at or below the poverty line? I refuse to accept for a minute that haveing 10% of America’s youth living at or below the poverty line is something for the Biden administration to celebrate in any way.


In addition, The Federal Reserve plays a major role in U.S. economic policy and can significantly influence the state of the economy in 2023. As inflation remains a pressing concern, the Federal Reserve faces the difficult task of deciding when and how to raise interest rates in this era of increasing interest rates due to Bidenomics.


The prospect of more interest rate hikes has raised questions about the state of the economy, and many are left wondering why the economy is in such a precarious position.


Make no mistake, Bidenomics has heightened tax disparities between states. Forbes reports that California now bears the heaviest income tax burden in the nation, a staggering 13.3%, while Florida enjoys a tax haven status with no state income tax. California’s corporate tax rate at 8.84% far exceeds Florida’s 5.5%.


These punishing taxes deter investment and innovation in California, leading businesses and individuals to seek refuge in lower-tax states like Florida.


Equally concerning is the unchecked rise in living and housing costs in California, exacerbated by Bidenomics. According to PolitiFact, California’s median home price in May 2021 reached a staggering $818,260, compared to Florida’s more reasonable $344,900. Rent is substantially higher in California, with a median monthly rate of $2,518 for a two-bedroom apartment, versus Florida’s $1,256.


Working-class Americans work tirelessly to make ends meet, yet they find themselves at odds with an economy that seems to be working against them. This government’s role in shaping the economy cannot be underestimated, and it’s essential to scrutinize whether the current policies truly serve the people.


The Bidenomics plan aimed to change the economy for the better but it’s an epic failure.


As the nation grapples with inflation and extremely high interest rates, it’s clear that these policies have fallen short of their promises by every single measurable benchmark. The recession forecast looms large, and Americans are left wondering about the steps a nation can take to achieve economic growth.


Furthermore, millions of Americans are being faced with tough decisions every week about whether to put gas in their car to get to work or food in their refrigerator. This is not the American dream that we all love so much, it’s America in decline.


Bidenomics may have promised to improve the financial well-being of Americans, but the reality is far from what was anticipated. Inflation, housing costs, sagging stock market and increasing interest rates have brought about a challenging economic landscape, with many struggling to make ends meet.


The American spirit is being crushed under the weight of inflation and soaring interest rates, stark reminders of the consequences of these policies. As we peer into the economic horizon of 2023, the looming recession is a haunting specter, casting doubt on the effectiveness of Bidenomics in delivering on its promises. Bidenomics is a resounding failure by every single indicator.

bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.
Bob Rubin Appears on One America News

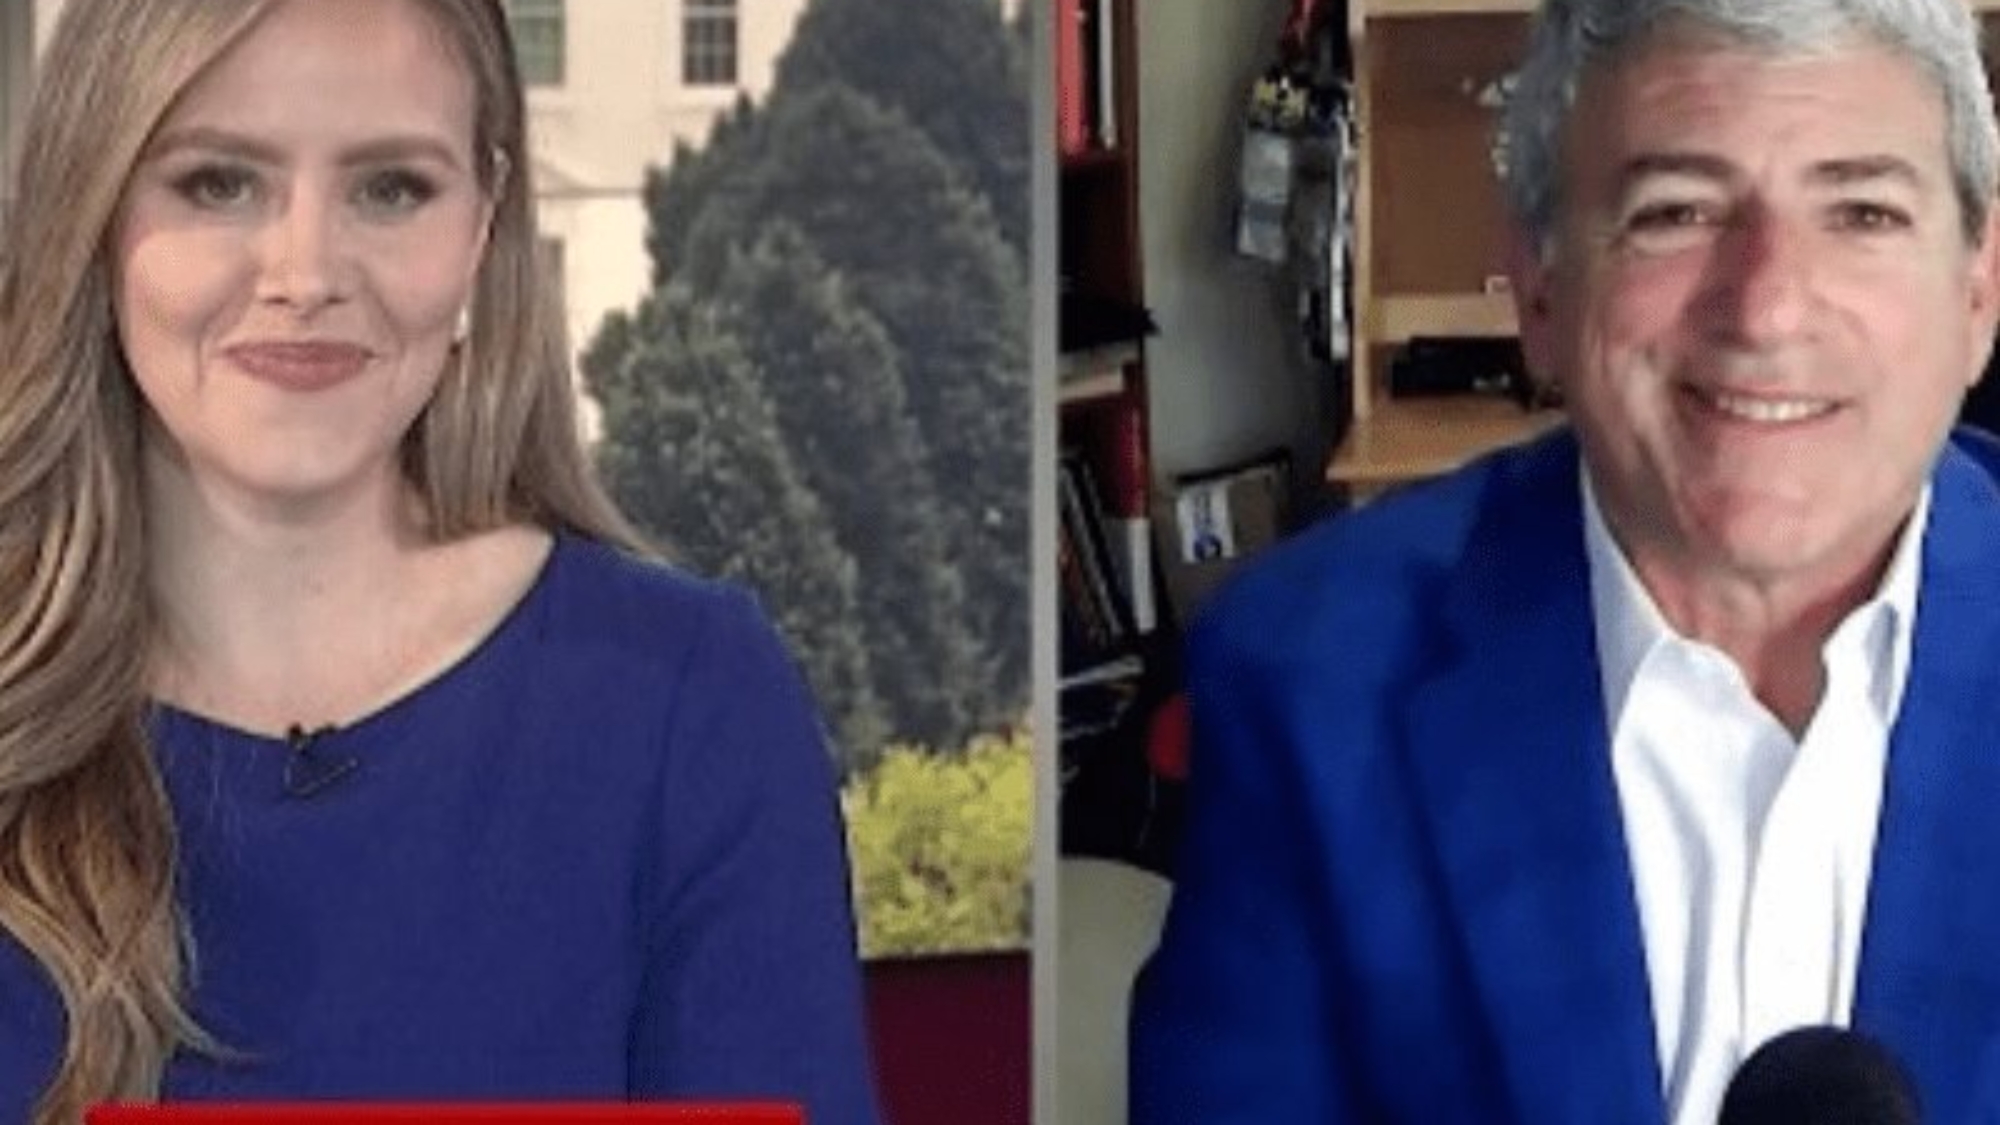
Bob Rubin Featured on One America News with Stella Escobedo

Bob Rubin Appears on One America News to comment on Vice President Kamala Harris comments about “Climate Anxiety”


Recently, Vice President Kamala Harris said that young Americans aren’t buying homes or having children because they have “climate anxiety.” One America’s Stella Escobedo spoke with Bob Rubin, founder and president of Rubin Wealth Advisors, about her comments.


This article originally appeared on: https://www.oann.com/video/oan-contribution/kamala-harris-gets-backlash-for-climate-anxiety-comment/


Check out the Instagram page of One America News for a short clip: https://www.instagram.com/reel/CxtH62BPNm8/?utm_source=ig_web_copy_link&igshid=MzRlODBiNWFlZA==

bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.
Bob Rubin Featured on Fortune Magazine!

Bob Rubin Featured on Fortune Magazine!

Finance giants BlackRock and Vanguard seem to be changing their approach to Environmental, Social, and Governance (ESG) investment strategies, increasingly rejecting shareholder proposals that focus on environmental and social issues.


Vanguard Group says it has only approved 2% of the environmental and social resolutions brought by shareholders in 2023, down from 12% last year, joining BlackRock in rejecting a significant number of climate and social items.


The firms’ strong support of ESG investing in recent years has led some financial advisory firms and a segment of the public to question whether financial institutions should concentrate on financial performance rather than other considerations.


BlackRock and Vanguard have a reputation for backing ESG initiatives. Yet it’s worth asking if this commitment was ever about ideology or simply a response to market demand. With recent statements from Blackrock CEO Larry Fink indicating a move away from controversial ESG terminology and a reported loss of approximately $4 billion in managed assets tied to ESG backlash, it’s clear that they’re feeling some heat. Though the loss may seem trivial for a company with over $9 trillion in assets under management, it’s far from pocket change.


The reconsideration by these two financial titans of their ESG commitments comes amidst increased attention from state-level financial authorities. Officials have questioned whether financial investment strategies should intersect so closely with environmental, social, and governance criteria. It appears these strategic shifts are being driven by a combination of public backlash and a focus on their bottom lines.

As an investor, your primary concern is the performance of your portfolio. Any factor that introduces increased volatility or lowers returns is something to be wary of. ESG, despite its intended social and environmental benefits, can add complexity that investors generally prefer to avoid. What you want as an investor is an appropriate risk-based investment strategy–one that is streamlined for delivering robust financial performance.


Financial institutions serve a critical role in managing clients’ portfolios–that should remain the central focus. It is of paramount importance that financial organizations stick to their core mission rather than diversify into complex societal debates.


While it may appear that BlackRock, Vanguard, and similar firms are shifting their attention toward traditional financial performance metrics, it’s still crucial to observe their actions carefully because they are industry leaders. Transparency is essential to ensure these major players are genuinely committed to the primary need of their investors: to focus on maximizing the returns and growth of their clients’ portfolios.


As industry leaders often set the trend, their actions may well indicate a broader shift in focus back to core financial strategies. Major financial firms have adopted ESG to keep up with the times–but they also saw it as an opportunity to make lots of money.


We can be cautiously optimistic that BlackRock and Vanguard are reverting to what they do best–optimizing client investments for financial growth.

bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.
Breaking Point How Failed Liberal Policies Propel the Flight to Red State Sanctuaries

Breaking Point: How Failed Liberal Policies Propel the Flight to Red State Sanctuaries

If you’re keeping tabs on the pulse of America, you’ve likely noticed a mass migration from blue states to red states. One of the most telling examples comes from San Francisco, where Nordstrom recently announced the closure of its flagship store, citing crime and public disorder as significant concerns. It’s a development that serves as an unfortunate testament to how liberal policies are transforming America’s big cities into shoplifters’ paradises. What’s happening in San Francisco is being replicated in many major cities in America.


At the heart of the matter is the failure of progressive governance to maintain law and order, paving the way for skyrocketing crime rates, surging poverty rates and plummeting quality of life. This hasn’t gone unnoticed. Financial giants like BlackRock are already drawing back from investing in “woke” ideologies such as Environmental, Social, and Governance (ESG) schemes, a trend that is bound to trickle down through the rest of the industry. 


What we are witnessing is not just a singular event but a broader shift that underscores why Americans, including large corporations, are packing up and heading to conservative strongholds. While BlackRock might be reconsidering its approach to ESG—a welcome change for those of us who have been critical of the industry’s focus on social justice over client portfolios—the bigger picture shows that Americans are getting fed up with failed policies.


San Francisco’s decaying public order—symbolized by Nordstrom’s unfortunate departure—sends a clear message. Financial institutions like BlackRock are one thing, but when retail giants start shutting down their stores in the heart of a bustling city, it’s an ominous sign that liberal governance is not only failing but driving away business.

As I’ve argued in my previous writings, financial institutions would do well to focus on their core competency, which is managing money and maximizing shareholder value. This focus is precisely what firms like Rubin Wealth Advisors offer to clients who are concerned about the direction in which this country is headed. Our mission is to be a sanctuary for politically conservative investors who want to safeguard their assets from the damaging effects of liberal policies and agendas.


The mass migration to red states isn’t just a demographic shift; it’s a monumental vote of no confidence in progressive governance. People are voting with their feet and their wallets, choosing to invest and live in areas where their values are respected, their safety is prioritized, and their businesses can operate without the burden of overreaching regulations and rampant crime.


In closing, the retreat of companies like Nordstrom and perhaps even BlackRock from woke ideologies and failing blue cities serves as a bellwether for the conservative movement. 


We can’t afford to let up now; the stakes are too high. It’s a collective call to action to preserve the America we know and love, and it’s a fight that we’re committed to at Rubin Wealth Advisors.


If you’re concerned about the future of your investments in a progressively unstable world, now is the time to align with financial advisors who share your values. We don’t have the luxury of complacency; the exodus from blue states to red states is an urgent reminder that action is needed. Let’s keep our foot on the gas pedal and continue to press for sensible governance, both in politics and in finance.


Check out a recent article to learn more about how big companies are backpedaling from their woke ideologies by clicking here.

bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.
financial institution

Unveiling Antisemitism: Financial Firms Single Out Israel

The following article comes from Bob Rubin’s  op-ed for JNS :https://www.jns.org/column/financial-services/23/8/3/307522/


Over the span of my long career as a financial advisor, I’ve witnessed a myriad of situations – clients amassing and losing fortunes, colossal institutions with billions in assets collapsing within 24 hours due to ceaseless mergers, and the oscillation between bullish and bearish markets. Yet, what remains unacceptable is the intrusion of financial institutions into culture wars and social justice matters.


Let’s be clear: the mission of a financial institution revolves around money and fiscal matters, not entangling itself in culture wars or the ever-changing landscape of social justice. The last thing I desire is for my clients’ accounts to suffer due to some far-left marketing manager pulling a misguided move akin to a “Bud Light” fiasco.


One of the culture wars that has infiltrated financial institutions pertains to the subtle boycott of Israeli companies. The recent case of Morgan Stanley, a global giant in brokerage and investment banking, downgrading Israel’s sovereign credit rating to a “dislike stance” last week serves as a notable example. Meanwhile, Moody’s cautioned of a “significant risk” stemming from political and social tensions that could negatively impact Israel’s economy and security situation.


But let’s pause and consider this: Did Morgan Stanley take a similar action with America’s sovereign credit rating as cities went up in flames during the Black Lives Matter protests, incurring billions in damage? Or did they adjust the sovereign credit rating of the Islamic Republic of Iran after the unjust execution of over 600 innocent Iranian citizens this year on baseless charges? The answer is an unequivocal no. However, peaceful protests in Israel regarding judicial reform have prompted major financial institutions to take shots at the Israeli government by altering their sovereign credit ratings.


While the aforementioned instances raise considerable concern, one of the most glaringly antisemitic incidents involving a major financial services company over the past year revolves around Morningstar’s targeting of Israeli companies. Morningstar, a global financial services company renowned for delivering independent investment research, data, and analysis to investors and financial professionals, has ventured into boycotting companies within the State of Israel.

Throughout my career, I’ve consistently and proudly supported the world’s only Jewish nation: the State of Israel, often referred to as the Startup Nation. It deeply troubles me that Morningstar, while ignoring the transgressions of countries like China or the Islamic Republic of Iran, continues to single out Israeli companies.


To delve into the past year’s interactions between Morningstar and Israeli companies, let’s explore the details. In October 2022, Morningstar unveiled additional measures to address concerns regarding anti-Israel bias raised by Jewish groups in the U.S. in relation to Sustainalytics’ ESG research products. Regrettably, the implementation of these “additional measures” faced delays.


A report in February 2023 by The Washington Free Beacon revealed that Morningstar, the financial ratings giant, had failed to follow through on its commitment to eliminate anti-Israel bias from its corporate ratings system. This was highlighted by the company’s continued blacklisting of firms associated with Israel, including Motorola Solutions and Elbit Systems, despite their contribution to Israel’s security sector and counterterrorism efforts.


Governor Ron DeSantis of Florida, in a recent address to the group Christians United for Israel, candidly remarked: “We [Florida] have also stood firmly against the BDS [Boycott, Divest, and Sanction Israel] movement. Now they’re trying to infuse anti-Israel policies into the so-called ESG criteria. First and foremost, ESG is a complete sham, and we’ve strongly opposed it in the state of Florida.”


I commend my governor for taking a resolute stance on this issue, as billions, if not trillions, of dollars flow through ESG-related assets. In this context, Morningstar’s attempt to divert these capital flows away from companies linked to Israel constitutes a direct economic assault on the nation.


From Morgan Stanley to Morningstar, there appears to be an unsettling fixation on singling out the sole Jewish state globally. This selective targeting undeniably qualifies as antisemitism. As a professional in the financial services sector, I believe it would be prudent for them to refocus on their core competency of serving clients and aiding them in managing their finances, rather than delving into contentious culture wars.

bob rubin

Are you concerned about inflation, ESG compliances, and the 2022 crypto crash?

Your investment portfolio can be affected by any or all of these factors.

Schedule an appointment with Bob Rubin, your dedicated, conservative financial advisor, for a free portfolio analysis today.

Get started by clicking the button below.